
Financial Planning for Retiring and Retired Military Officers
We bring your pension, TSP, and civilian income into one plan, whether the retirement decision is ahead of you or behind you.
Are Your Military Benefits and Civilian Income Actually Coordinated?
Career military officers face financial decisions that start before the retirement date and keep coming after it. You may recognize yourself here:
You may be approaching your retirement date with pension, Survivor Benefit Plan (SBP), and Thrift Savings Plan (TSP) elections that cannot be undone.
Or perhaps you retired years ago, and no one has looked at those elections since the day you signed them.
A civilian or defense-contractor paycheck has landed on top of your pension, and the tax bill is larger than you planned for.
Your TSP is still sitting where you left it, and you are not sure whether it belongs there.
You want to know whether the next career move or the choice to stop working is affordable for you and your family.
At Occidental Asset Management, we help career military officers turn pension, TSP, and civilian income into one coordinated plan.
Decide What Comes Next, and When
Build Income That Lasts
We coordinate your pension, savings, and any civilian earnings into an income plan, so continuing to work remains a choice.
Stay Ahead of Taxes
We plan across your pension, TSP, and any employer plan, including the years when a salary and a pension overlap.
Gain Confidence & Control
You set the timeline for where you live and when you stop working, with the numbers behind the decision.
Our goal is to help you:
How It Works
1
Start the Conversation
We review your accounts, benefits, and financial goals, then complete the paperwork to get started.
2
Build Your Full Picture
We gather your financial details and work through your open questions.
3
Plan & Stay on Track
We present a tailored financial plan, then meet regularly to adjust it.
Services
You receive comprehensive planning designed to help you with:
-
Coordinating the moving pieces of your financial life.
-
Comparing your election options before they lock in.
-
Deciding whether to keep or roll your TSP.
-
Coordinating all your income sources into a sustainable plan.
-
Managing the year civilian income meets your pension.
-
Modeling how a civilian role changes your plan.
-
Building and monitoring a portfolio for your goals.
-
Timing your benefit alongside your pension and savings.
-
Minimizing financial risk and planning for your family's future.
Who You’ll Work With
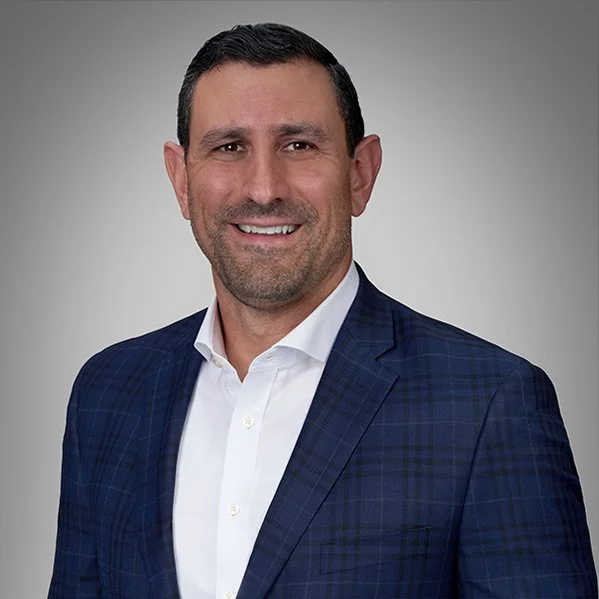
James Griffin, MBA, CFP®
Occidental Asset Management works with career military officers, both those approaching a retirement date and those already drawing retired pay, to bring pension, survivor benefits, TSP, and civilian income into one plan.
James Griffin, MBA, CFP®, is the lead advisor for this work. With nearly two decades in financial services, his job is to speak both languages, military benefits and civilian finances, and to get every piece onto one table where you can see how it fits together. That includes the decisions still ahead of you and the ones already made, which often have not been revisited since the day they were signed.
In practice, that means:
Walking through the elections that cannot be undone, including the ones already made, so you know what each one locked in.
Planning the years when a civilian salary sits on top of retired pay, before the tax bill arrives rather than after.
Turning a TSP balance and other savings into income that works alongside the pension and managing it as things change.
James works from Occidental’s Orlando office, near the military simulation commands and defense contractors where many retired officers build their second careers. He also works with Clients nationwide virtually.
Where We Start
-
Pension, SBP & TSP Compared
A side-by-side look at your election options or a review of the ones already in place.
-
Paycheck, Pensions & Savings Aligned
One view of how your income sources work together now and in the years ahead.
-
Clear Answers on Taxes & Ti
An answer on the tax impact of your current or upcoming income mix.
Is Occidental Asset Management Right for You?
We may be a good fit if you:
Are a career military officer, retiring soon or already retired, who wants the pension, TSP, and civilian income decisions handled together.
Have investable assets of more than $500,000, which for many officers is a TSP balance combined with other savings.
Want a long-term, ongoing relationship with a financial advisor rather than a single meeting.
If that sounds like where you are, we would welcome the chance to talk.

Get Every Piece on One Table
Are you ready to stop guessing at how your pension, TSP, and civilian income fit together? Take the first step by scheduling an introductory call.
Memberships & Associations
Frequently Asked Questions
-
Yes. While we work with a range of Clients, we have particular depth in serving career military officers retiring after 20-plus years of service, as well as their families. These are Clients facing a specific set of one-time decisions, like a pension election, a Survivor Benefit Plan (SBP) choice, and what to do with a Thrift Savings Plan (TSP) balance, and can benefit from planning built around a military-to-civilian transition rather than a general financial plan.
-
We provide financial planning and investment management built around income strategy, tax planning, Social Security planning, and estate and risk planning. For military Clients, that often includes comparing pension and SBP election options, deciding whether to keep or roll a TSP balance, and planning around a civilian paycheck when that's part of the picture. We coordinate income, taxes, and investments so they work together rather than being handled separately.
-
We offer both. Financial planning addresses income, taxes, and long-term goals, while investment management builds and monitors the portfolio that supports that plan. For retiring officers, the two are especially connected, since a pension election or TSP decision can change how a portfolio should be built. The same applies to a civilian or defense-contractor paycheck, which can shift how much a portfolio needs to generate versus how much it can keep growing.
-
A fiduciary is legally required to act in a Client's best interest, rather than recommend products that pay the advisor more. Occidental Asset Management is a fiduciary, fee-only Registered Investment Advisor (RIA), meaning we do not receive commissions or outside compensation. This applies throughout our planning, including pension, SBP, and TSP decisions, where the recommendation should reflect your situation, not a product's payout.
-
Occidental Asset Management is fee-only. We are paid directly by our Clients and do not earn commissions or accept compensation from outside institutions for the recommendations we make. That structure is designed to keep advice focused on your transition and your goals rather than any product sale.
-
Our investment approach favors diversified, research-driven strategies, with attention to cost and ongoing monitoring, rather than chasing short-term performance. For officers, that can mean building a portfolio that works alongside a pension, Social Security, and any civilian income, rather than one built around accumulation alone. Investing involves risk, including the potential loss of principal, and past performance does not indicate future results.
-
Occidental Asset Management generally works with Clients who have at least $500,000 in investable assets. For many officers, this level is reached through a combination of TSP balances, other savings, a civilian employer's retirement plan, and sometimes a spouse's retirement accounts, so it can be worth having a conversation even if your assets are spread across several accounts.
-
We believe we can be most effective through an ongoing advisory relationship, one in which the plan and the pension, SBP, and TSP decisions within it can be revisited as your transition unfolds and circumstances change. For that reason, we generally do not offer financial planning on an hourly or project basis.
-
We work with Clients both in person and remotely, with locations in Florida, Hawaii, California, Washington, and Colorado. Many of our military Clients relocate during or after their transition, so virtual meetings help us continue working together as your next assignment or job takes you elsewhere.
-
Yes. We offer an introductory call to discuss your situation, concerns, upcoming decisions, and whether our approach is a good match before any commitment is made. This is a chance to ask questions about the pension election, SBP, TSP, or anything else on your mind.
-
Occidental Asset Management has locations in Burlingame and San Francisco, California; Boulder, Colorado; Altamonte Springs (Orlando), Florida; Bellevue (Seattle), Washington; and Lihue, Hawaii. Because military officers often relocate during and after their transition, we also serve Clients nationwide through virtual meetings.
-
The Survivor Benefit Plan (SBP) is an optional military pension election that continues a portion of your retired pay to your spouse after your death, in exchange for a reduction to your pension while you are alive. The decision is generally irreversible once made, so it deserves a close look at your other assets and income sources before you elect it. We help retiring officers weigh the SBP alongside other survivor income options, like TSP balances and life insurance, so the choice fits the bigger picture.
-
Whether to keep your TSP in place or roll it into an IRA depends on factors such as investment options, fees, and how the balance fits with your broader retirement income plan. Neither option is automatically better, and the right choice depends on your financial picture and the timeline for your next paycheck. We walk through the trade-offs of each option as part of transition planning.
-
Adding a civilian or defense-contractor salary on top of a military pension can push retiring officers into a higher tax bracket than they expect, especially in the first year of dual income. Planning ahead, through withholding adjustments, retirement account contributions, or timing decisions, can help manage that impact before it shows up at tax time. This is a common issue we help retiring officers plan for during their transition year.
-
Yes. Many retiring officers consider a return to aviation, a defense-contractor role, or a slower-paced position, and each option affects income, taxes, and how long a portfolio needs to last. We model these different paths against your pension, TSP, and savings so you can see the trade-offs before committing to one.